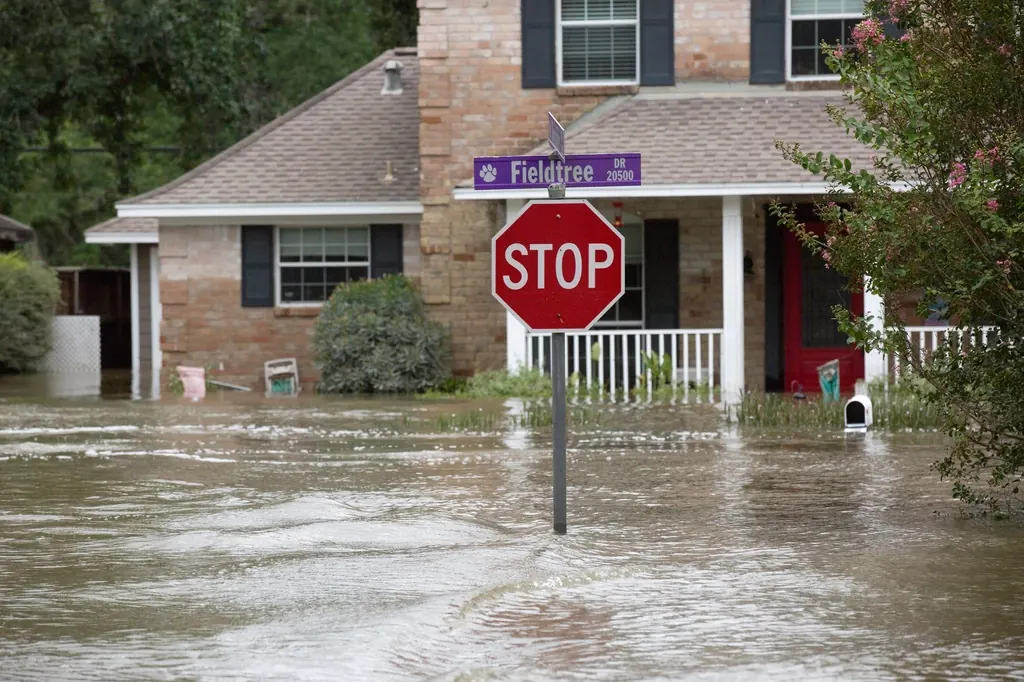
Why the split matters so much in Mississippi
Hurricane Katrina pushed storm surge miles inland across Hancock, Harrison and Jackson counties while also tearing roofs apart with wind. Homeowners and wind policies generally cover wind and wind-driven rain, while flood and surge are excluded and handled — if at all — by a separate flood policy. Many claims after 2005 turned on that allocation, and the same question returns with every Gulf storm.
How the estimator works
- The wind share of the damage, minus the named-storm deductible, is paid by the wind policy up to Coverage A.
- The flood share, minus the flood deductible, is paid by the flood policy up to its building limit.
- Anything above limits or inside deductibles — or flood damage with no flood policy — is left unpaid.
Illustrative figures only. Real allocations depend on evidence, policy wording (including any anti-concurrent causation clause) and the law that applies.
Appraisal can value the wind damage once coverage for it is accepted. It doesn’t decide whether damage was caused by wind or flood when that is a coverage dispute — that question may need an attorney. Read wind vs. water after Katrina for more.
Evidence that moves the split
Interior water lines, debris direction, missing roof coverings, wind-blown openings and a timeline of when water arrived all matter. Our hurricane and named-storm appraisal work starts with that evidence.
About this estimator
Does this tool tell me the right split for my house?
No. It shows how sensitive your recovery is to the split. The actual allocation depends on evidence and policy terms.
What if I don’t have flood insurance?
Tick the box and the flood share shows as unpaid. That makes clear how much depends on documenting wind damage thoroughly.
Is the NFIP limit really $250,000?
Standard NFIP building coverage for a single-family home is capped at $250,000; some owners buy excess flood coverage privately.