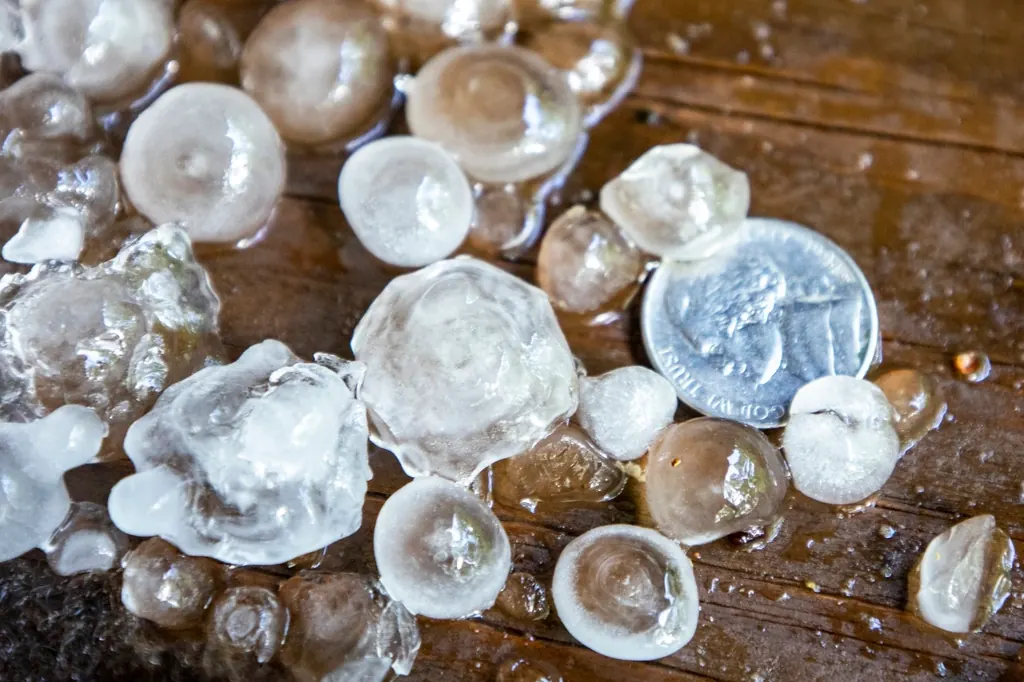
Hail and wind on Mississippi roofs
Spring storm lines cross the state every year, and hail can bruise shingles from the Delta to the Pine Belt. Wind adds creased and missing tabs, especially on older three-tab roofs. Architectural shingles hide hail bruising better than older styles, so damage that’s obvious up close can be easy to miss from a ladder at the eave.
Metal roofs are common on farm buildings in the Delta, on newer homes in rural counties and on many churches. Hail can dent panels and trim. Some policies carry a cosmetic-damage endorsement that limits payment for dents that don’t affect function, so read your endorsements before assuming a metal roof claim is a pricing dispute.
Timing matters too. Carriers often ask when the damage happened and compare your claim to storm reports for your area. A roofer’s inspection notes, dated photos and any earlier inspection reports help tie the damage to a specific storm rather than to age. If your roof was inspected when you bought the house, dig that report out; it can show the roof’s condition before the storm and answer wear-and-tear arguments before they start.
Line items that tend to disappear
When we review roof estimates, the same accessories go missing again and again:
- Drip edge at the eaves and rakes, often required by manufacturers and local code on replacement.
- Starter strip along the eaves and rakes, separate from field shingles.
- Ridge cap and ridge vent, priced by the linear foot rather than lumped into the field.
- Ice-and-water shield in valleys and around penetrations where the manufacturer or code calls for it.
- Steep and high charges for pitches above walkable slopes and for two-story eaves.
- Flashing at walls, chimneys and skylights, plus pipe jacks and vent caps.
- Waste factor that reflects hips, valleys and cut-up roof planes.
- Overhead and profit when the job needs a general contractor.
Our roof pitch and squares calculator shows how pitch changes the true area of a roof compared with its footprint.
Repair versus replace, and matching
Carriers often approve a few slopes or a set number of shingles. That can be reasonable when replacement material blends in. But many shingle lines have been discontinued, and new shingles from a different run or brand rarely match a weathered roof. Whether your policy requires a uniform appearance is partly a coverage question; the cost of a matching repair is an amount-of-loss question appraisal can price.
Brittle shingle and repairability
Older shingles can crack when lifted, making spot repairs impossible without damaging the surrounding roof. We document repairability on site so the discussion rests on evidence, not opinion.
Most roof disputes shrink or grow on the measurements. We verify squares, pitch, edges and penetrations on the roof itself before comparing prices, so both appraisers start from the same facts.
Code items and older roofs
Replacing a roof can trigger code requirements: added underlayment, drip edge or ventilation changes. Whether those costs are covered often depends on an ordinance or law endorsement. Where coverage exists, the cost belongs in the estimate. We also note decking that must be replaced when tear-off exposes rot or spaced sheathing under old shingles.
Getting started on a roof claim
Send us the carrier’s estimate, your policy and any roofer’s bid. We’ll tell you whether the gap looks like a measurement problem, a missing-items problem or a pricing problem. We also check whether the right deductible was applied, since some policies carry a separate wind or hail deductible that differs from the all-other-perils amount. If you only need a second opinion, our carrier estimate review may be enough. Homeowners in the fast-growing northwest corner can see our Southaven and DeSoto County page.
Available across Mississippi
Roof & Hail Claim Appraisal is available statewide. Inspections are scheduled around your timeline in places such as Hattiesburg, Southaven, Tupelo, Meridian.
Roof & Hail Claim Appraisal questions
Is hail damage on architectural shingles hard to prove?
It can be, because the granule loss and bruising are subtle from a distance. Close-up photos, test squares and notes on the shingle’s condition make the damage easier to document.
Can appraisal force full roof replacement for matching?
Appraisal can price a matching repair or a full replacement. Whether the policy requires uniform appearance can be a coverage question for a Mississippi attorney.
Does a named-storm deductible apply to hail?
Usually not, because a named-storm deductible is tied to a named storm. Many policies have a separate wind or hail deductible, so check your declarations.