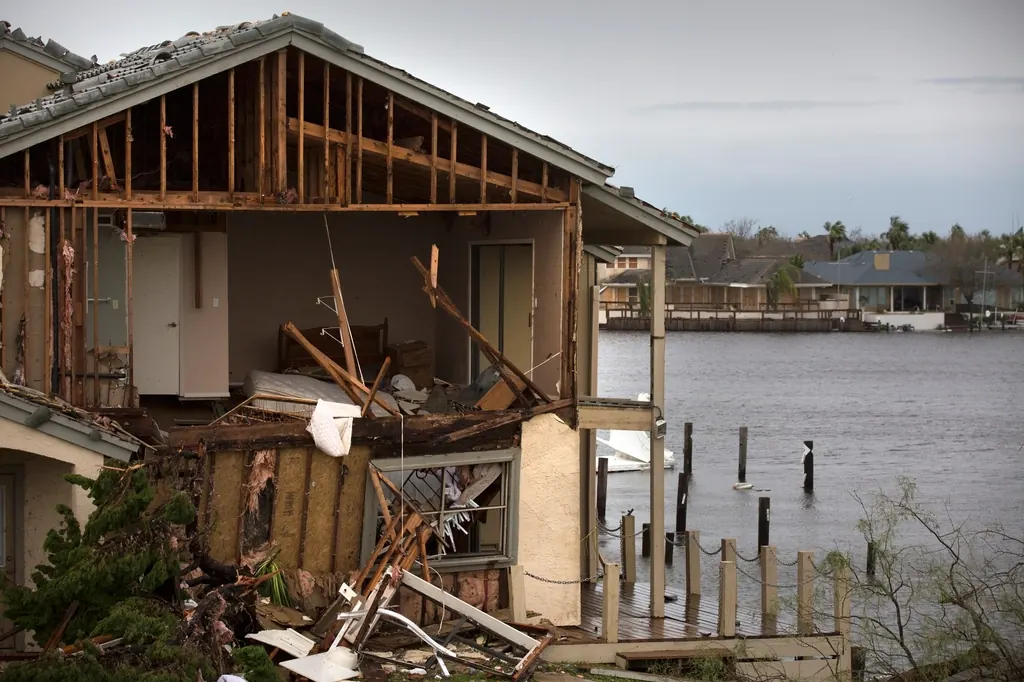
Three policies, one house
In Hancock, Harrison, Jackson, Pearl River, Stone and George counties, many homeowners can’t buy wind coverage on a standard homeowners policy. The usual arrangement looks like this:
- A homeowners policy that excludes wind and hail. It covers fire, theft, liability and other perils.
- A wind and hail policy from the Mississippi Windstorm Underwriting Association (MWUA). MWUA is the residual-market insurer for wind in those six counties.
- A separate flood policy, usually through the National Flood Insurance Program. Storm surge and rising water fall here, not under wind.
Some owners have private wind coverage instead of MWUA, and some have no flood policy at all. Pulling every declarations page is the first step on any Coast hurricane claim.
Where appraisal fits, and where it stops
After a hurricane, the big question is often what caused the damage: wind, which the MWUA or wind-inclusive policy covers, or water, which only a flood policy covers. That is a causation and coverage question. Appraisal generally can’t decide whether a loss is flood or wind, and it can’t override an anti-concurrent-causation clause. Those arguments go to counsel or a court.
What appraisal can do is value the wind portion. If your wind carrier agrees that wind tore off the roof, broke windows and let rain in, but pays less than that damage costs to repair, the appraisal clause in the wind policy can set the amount. A careful scope separates wind damage, such as roof covering, interior water from roof openings and blown-out glass, from surge lines and flood damage below them. The wind-water split estimator shows how that separation affects the numbers.
Hurricane Katrina, on August 29, 2005, pushed catastrophic surge across Waveland, Bay St. Louis, Pass Christian, Long Beach, Gulfport, Biloxi, Ocean Springs and Pascagoula, and its winds reached Hattiesburg, Laurel and Meridian. Years of wind-versus-water litigation followed. Clear documentation of what the wind did before the water arrived remains the most useful thing a Coast owner can have.
Deductible math comes first
Hurricane and named-storm deductibles on and near the Coast are often a percentage of Coverage A, commonly 2% to 5%. Illustrative example: on a home insured for $300,000, a 5% deductible is $15,000 before the carrier pays anything. That makes the size of the gap especially important: appraisal on a disputed amount below the deductible may not help at all.
Try the named-storm deductible calculator before deciding whether to pursue appraisal.
Storms that shaped Coast claims
Hurricane Camille made landfall near Pass Christian and Bay St. Louis on August 17, 1969, as a Category 5. Isaac in August 2012 brought rain and surge. Nate made landfall near Biloxi as a Category 1 in October 2017. Zeta, on October 28, 2020, came ashore in Louisiana but drove strong wind across the Mississippi Coast. Ida in August 2021 made landfall in Louisiana and brought wind and tree damage to southwest Mississippi.
Disputes we see after hurricanes
Beyond wind versus water, Coast estimates often fight over code upgrades on raised homes, matching on partially damaged roofs and siding, interior water from wind-created openings, and additional living expense while repairs wait on contractors. For a deeper history, read wind vs. water after Katrina.
Inland owners face their own version of these fights. Katrina’s winds reached far beyond the six southern counties, and later storms such as Ida brought wind and falling trees to southwest Mississippi. Away from the Coast there’s usually no MWUA policy and less flood overlap, so the dispute is more often about scope and price on a standard homeowners policy — exactly the kind of question appraisal is designed to answer.
Available across Mississippi
Hurricane & Named Storm Appraisal is available statewide. Inspections are scheduled around your timeline in places such as Gulfport, Biloxi, Hattiesburg, Southaven.
Hurricane & Named Storm Appraisal questions
Can appraisal decide whether my damage was wind or flood?
Generally no. Wind-versus-flood causation is a coverage question, but appraisal can value the wind damage once the wind carrier accepts that portion of the claim.
Does an MWUA policy have an appraisal clause?
Wind policies commonly include an appraisal provision. Read your MWUA policy form and endorsements to confirm the exact wording and deadlines.
Do named-storm deductibles apply inland, like in Hattiesburg?
Many policies statewide carry hurricane or named-storm deductibles, not only on the Coast. Your declarations page shows whether yours does and how it is calculated.
What if my wind carrier and flood carrier both say the other one owes?
That is a coverage dispute, and a Mississippi attorney is the right first call. Accurate documentation of wind damage helps either way.