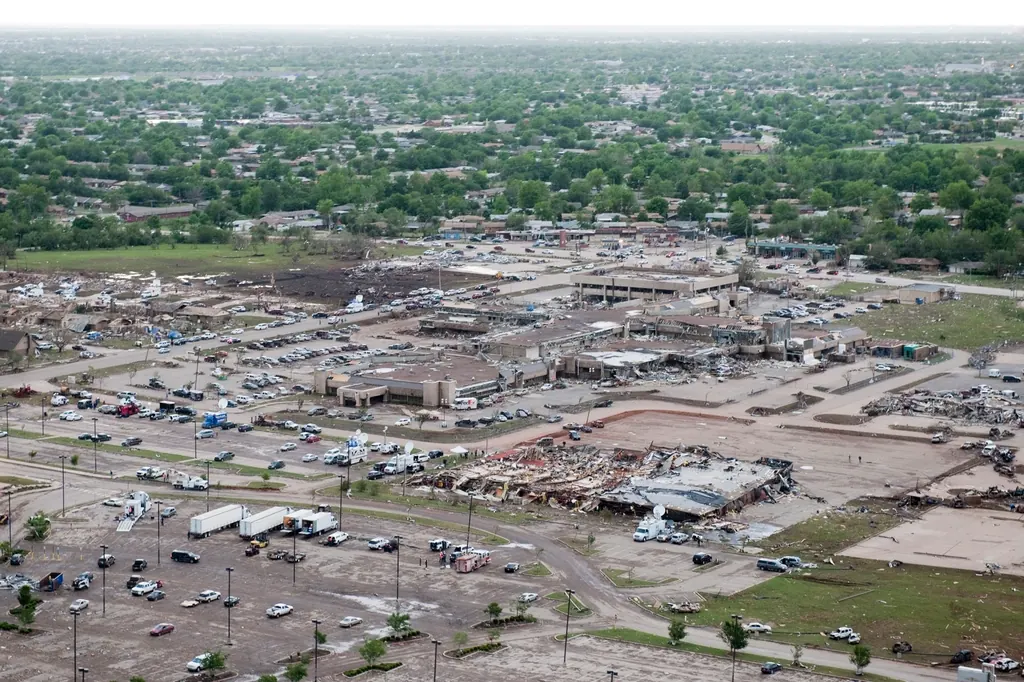
A state shaped by tornadoes
Mississippi’s tornado history runs from the Tupelo tornado of April 5, 1936, one of the deadliest in US history, through the Vicksburg tornado of December 5, 1953. More recent storms include the Yazoo City EF4 on April 24, 2010, the Smithville EF5 in Monroe County on April 27, 2011, and the Hattiesburg EF4 on February 10, 2013, which crossed the University of Southern Mississippi and Oak Grove areas.
The Louisville EF4 in Winston County struck on April 28, 2014, the same day an EF3 hit Tupelo. Columbus took an EF3 on February 23, 2019. The Easter Sunday outbreak of April 12, 2020, brought an EF4 near Bassfield and Soso and wide damage across the Pine Belt. On March 24, 2023, an EF4 devastated Rolling Fork in Sharkey County and Silver City in Humphreys County, and the same storm system hit Amory.
Straight-line winds from thunderstorm lines cause similar damage on a smaller scale and are just as likely to produce a dispute.
Where partial-loss estimates fall short
A house on the edge of a tornado path can look intact while its structure has shifted. Carriers sometimes estimate visible damage — shingles, siding, broken windows — and miss what’s behind it.
- Racked walls, shifted trusses or a roof lifted off its plates.
- Cracked brick veneer and pulled wall ties.
- Doors and windows that no longer close because framing moved.
- Debris impacts on roofs, siding, HVAC units and vehicles under carports.
- Glass and insulation scattered through wall cavities and attics.
- Fences, sheds, barns and outbuildings under other structures coverage.
We document these items with measurements and photos and, where needed, recommend that a structural engineer weigh in before the appraisers compare numbers.
Interior damage deserves the same attention. Pressure changes and wind-driven rain can loosen ceiling drywall, soak insulation and stain finishes in rooms that look fine at first glance. Rural properties in the Delta and East Central Mississippi add another layer: barns, equipment sheds, grain bins and long runs of fencing that a quick inspection may skip entirely.
Repair or rebuild
Sometimes the dispute is whether a building can be repaired at all. If repair would cost close to replacement, or if code would require so much upgrading that the structure has to be rebuilt, the valuation changes completely. Appraisal can set the cost to repair versus the cost to replace. Whether the policy pays a total-loss amount can involve coverage questions, especially under an ordinance or law endorsement.
Code upgrades after a tornado
Rebuilding a damaged home often triggers current codes for wiring, framing connections and roof decking. Many policies cover some of that cost under ordinance or law coverage, usually with a separate limit. We price code-required work separately so the award shows it clearly.
Photograph every elevation, the roof and each room before cleanup crews arrive, and keep a few damaged materials if you can. Once the debris is gone, so is much of the evidence an appraiser needs.
Debris, contents and living costs
Tornado claims also bring debris removal, which some policies cap or fold into the dwelling limit, plus contents losses and additional living expense when the home can’t be lived in. Each has its own dispute pattern, and each can be part of the amount appraisal decides when coverage isn’t in question.
Our guide to documenting tornado damage walks through what to capture in the first days. Many tornado losses also involve trees on structures; see fallen tree claim appraisal. Owners in the Golden Triangle can read our Columbus and Lowndes County page.
Available across Mississippi
Tornado & Wind Damage Appraisal is available statewide. Inspections are scheduled around your timeline in places such as Pascagoula, Vicksburg, Columbus, Greenville.
Tornado & Wind Damage Appraisal questions
Is a tornado claim subject to my hurricane deductible?
Usually not unless the tornado was part of a named storm and your policy ties the deductible to that event. Check your declarations for separate wind, hail or named-storm deductibles.
Can appraisal decide whether my house is a total loss?
Appraisal can value the cost to repair compared with the cost to replace. Whether the policy pays as a total loss can involve coverage terms a Mississippi attorney should review.
What if straight-line wind, not a tornado, caused the damage?
Most property policies treat windstorm damage the same way whether it came from a tornado or straight-line wind, so the valuation process is the same.