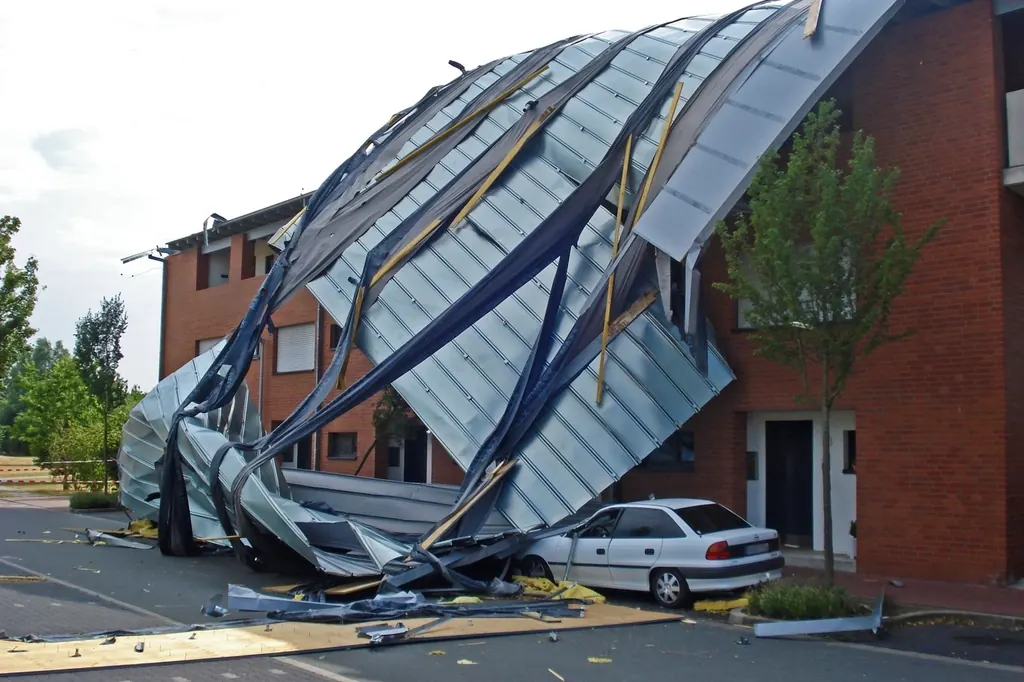
Mississippi’s tornado record and why the first days matter
Few states see tornadoes as often or as late in the year as Mississippi. The Easter Sunday outbreak on April 12, 2020 sent an EF4 through the Bassfield and Soso area of Jefferson Davis, Covington and Jasper counties and left wide damage across the Pine Belt. On March 24, 2023, an EF4 tore through Rolling Fork in Sharkey County and Silver City in Humphreys County, and the same storm system went on to hit Amory in Monroe County.
After a storm like that, the first priority is safety. Once everyone is safe, the next few days shape your claim. Debris gets hauled off, tarps go up and temporary repairs begin, and every one of those steps can erase evidence. A good record made early makes every later conversation, including an appraisal, easier.
Your tornado documentation checklist
Work from the outside in, and from big picture to detail. Try to capture each item before anything is moved or repaired, when it is safe to do so.
Outside the house
- Wide shots of every side of the building from the street and yard, then closer shots of damage.
- Roof photos from the ground or a drone: missing shingles, exposed decking, displaced ridge caps, damaged vents and flashing.
- Siding, gutters, soffits, fascia, windows and screens, with a few shots that show scale.
- Fences, sheds, carports, barns and other detached structures, which usually fall under Coverage B.
- Fallen trees, especially any that hit the house or block the driveway.
Inside the house
- Every room, even ones that look fine, so later water stains have a “before” photo.
- Ceiling stains, wet insulation, cracked drywall and shifted trim.
- Attic framing, decking from below and any daylight showing through.
- Damaged contents, photographed in place before cleanup, with brand and model labels where you can.
Paper trail
- Date and time of the storm, and when you reported the claim.
- Receipts for tarps, board-up, tree work, hotel stays and meals away from home.
- Names and dates for every adjuster, contractor and engineer visit.
- Copies of any National Weather Service survey information for your area.
Most policies require reasonable steps to prevent further damage. Tarp the roof and dry out wet areas, but take photos and video before and after, and keep every receipt.
Tornado or straight-line wind: does it change the claim?
After a storm, the National Weather Service surveys damage and assigns an EF rating to confirmed tornadoes. Some damage turns out to be from straight-line winds instead, which can be just as destructive across a wide area.
For most homeowners and commercial policies, that distinction rarely changes coverage. Both are typically treated as windstorm, so the same coverage and deductible usually apply. Where it can matter is on policies with a separate wind or named-storm deductible, or in arguments about whether a particular piece of damage came from that storm or from older wear. Read your declarations page and ask the adjuster in writing which deductible was used.
Organizing the record so others can follow it
A thousand unlabeled phone photos are hard for anyone to use. Spend an evening sorting them into folders by area: roof, each side of the house, each room, outbuildings and contents. Rename a few key images so the file name says what they show, such as “north slope missing shingles” or “bedroom 2 ceiling stain.” Keep the originals untouched so the date and time data stays intact.
Next, start a simple written log. Each entry needs only a date, who you spoke to, and what was said or promised. If an adjuster says a supplement will be reviewed, or that an engineer will inspect, note it. Send a short email afterward confirming the conversation. When an estimate review or an appraisal comes later, this log and the sorted photos often do more to support the scope than any single document.
Common gaps in tornado estimates
Tornado estimates written in the rush after a big outbreak often miss things. When you review the carrier’s numbers, look for:
- Roof slopes left off because only the most obvious side was inspected.
- Missing line items for drip edge, starter strip, ice and water shield or code-required items.
- Siding or shingles priced as spot repairs when matching material isn’t available.
- Interior damage from rain that entered through wind openings days after the storm.
- Debris removal and tree work, which may have separate limits.
- Additional living expense if the home wasn’t livable.
Our guide to reading an estimate line by line explains how to spot these gaps, and the roof pitch and squares calculator helps you check roof quantities.
Keeping the claim on track
Report the claim promptly, even if you don’t know the full extent yet. Ask for a copy of the adjuster’s estimate and photos. If later inspections or repairs uncover more damage, submit a supplement with photos and a written description.
If the carrier accepts the claim but you are far apart on the amount, appraisal may be an option under your policy. Watch your deadlines: policy timeframes for repairs and recoverable depreciation, and Mississippi’s general three-year limitation period for many contract claims, which you should confirm with a Mississippi attorney for your situation.
Our tornado and wind damage appraisal page explains how we approach these files, from Hattiesburg to Tupelo. If you are in the Pine Belt, see our Hattiesburg page.